A CHOICE Arrangement, short for Custom Health Option and Individual Care Expense Arrangement, is the new federal name for the Individual Coverage HRA (ICHRA). You set a fixed monthly allowance, employees choose their own individual plan, and reimbursements are tax-free.
The Basics
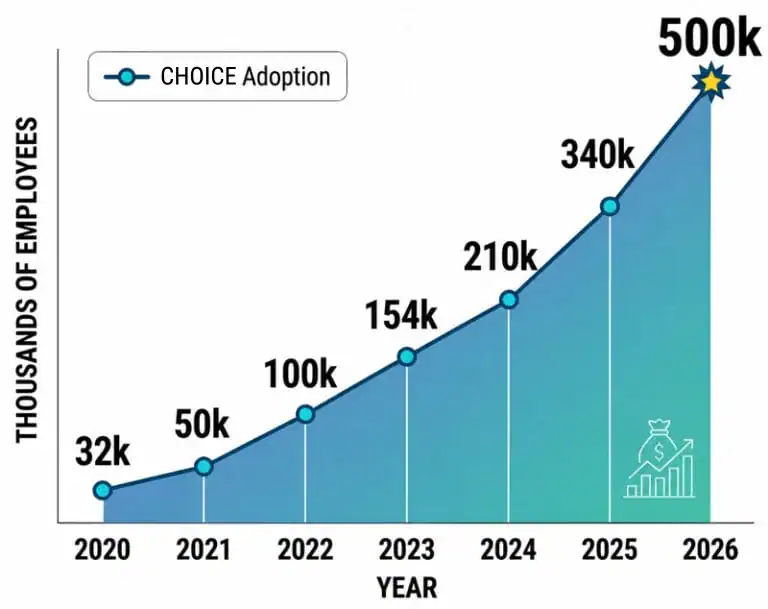
A CHOICE Arrangement — short for Custom Health Option and Individual Care Expense Arrangement, and formerly known as ICHRA — replaces traditional group coverage with a tax-free employer allowance that employees use to buy individual insurance. Driven by companies seeking relief from annual group rate increases, adoption has grown nearly 10× since HHS authorized the model in 2020, according to HHS and KFF reports.
You Set a Monthly Amount
As the employer, you decide how much to contribute per employee per month — by class if needed (full-time vs. part-time, salaried vs. hourly). That is your maximum cost. Period.
Employees Shop Their Own Market
Each employee shops the ACA marketplace or off-exchange individual plans in their state. They choose based on their own doctors, prescriptions, and family needs.
You Reimburse Tax-Free
Employees submit proof of premium. You reimburse up to your set amount — fully tax-deductible for you, tax-free income for them. No W-2 impact.
CHOICE Arrangement Employer Adoption (thousands)
Source: HHS/EBSA reports · *2026 projected
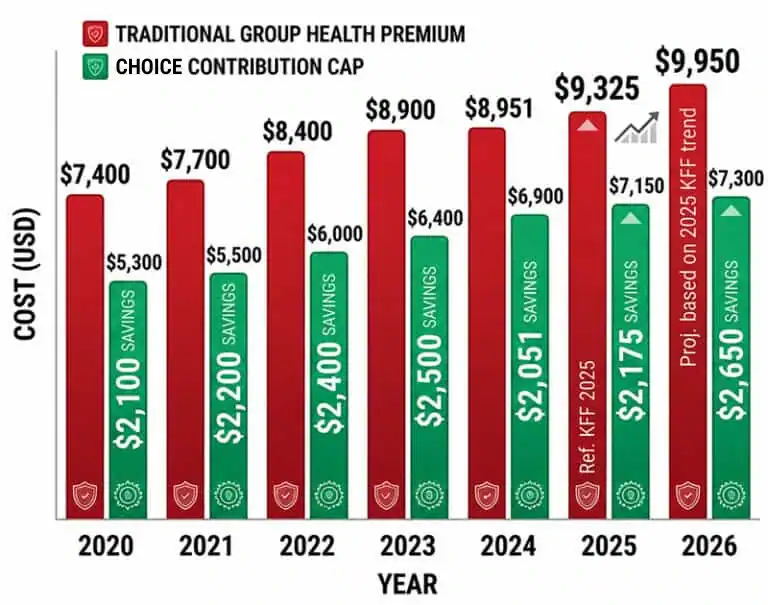
Avg. Employer Cost Per Employee Per Year
Source: KFF Employer Health Benefits Survey · CHOICE Arrangement = employer-set contribution cap
By the Numbers
CHOICE stands for Custom Health Option and Individual Care Expense Arrangement. Originally authorized by HHS in 2020 and renamed by CMS and the SBA in 2026, it replaces group coverage with a tax-free employer allowance that each employee uses to buy their own insurance.
870%
CHOICE Arrangement employer growth since 2020
$1,200+
Avg. annual savings per employee vs group
1
Minimum employees required for a CHOICE Arrangement (at least 1 W-2 employee)
100%
Of CHOICE Arrangement contributions are tax-deductible for employers
Key Flexibility Feature
Set Different Contribution Amounts by Employee Class
As the employer, you decide how much to contribute per employee per month — by class if needed (full-time vs. part-time, salaried vs. hourly). That is your maximum cost. Period.
By Employment Type
Full-time employees: $600/mo · Part-time employees: $300/mo · Seasonal workers: $200/mo
Set richer allowances for the roles you most need to attract and keep, and still offer a benefit to part-time and seasonal staff.
By Geographic Location
New York office: $700/mo · Kentucky office: $450/mo · Remote/home-state: varies
Insurance costs vary significantly by state. Contributions can reflect local market rates.
By Age
Under 30: $350/mo · Age 30–49: $500/mo · Age 50+: $750/mo
ACA individual premiums increase with age. A CHOICE Arrangement lets you scale contributions to match — so older employees aren’t underserved.
By Job Category
Management: $650/mo · Administrative: $450/mo · Field/labor: $400/mo
Employers can define classes by FLSA status, pay grade, or job classification as defined in their plan document.
Important: Employee classes must be defined consistently and cannot be designed to discriminate based on health status. We help you structure classes that are both IRS-compliant and optimized for your workforce.
Common Questions
A CHOICE Arrangement (Custom Health Option and Individual Care Expense Arrangement) is the federal government’s new name for what was previously called an ICHRA, or Individual Coverage Health Reimbursement Arrangement. CMS and the SBA adopted the CHOICE name in September 2026; the rules did not change. First established by HHS in 2020, it lets employers reimburse employees tax-free for individual health insurance premiums and qualifying medical expenses — replacing or supplementing traditional group coverage.
Yes — it’s one of the biggest advantages of a CHOICE Arrangement over group plans. Employees in any state shop their local individual market. You set one contribution policy that applies everywhere, and we handle enrollment support in all 50 states.
Keep Exploring
More on how CHOICE Arrangements and our services can work for your business.
A side-by-side look at budget control, plan choice, renewal risk and participation rules.
The signs a CHOICE Arrangement fits: steep renewals, diverse teams, tight budgets and fast growth.
Benefit design, employee enrollment and year-round support from a dedicated advisor.